Vehicle Finance Check
Is there money owing on the car?
About 1 in 10 used vehicles checked with MotorRegistry has finance owing.
A vehicle finance check searches the Personal Property Securities Register (PPSR) for any loan or security interest registered against a car. If you buy a car with money owing on it, the lender may be able to repossess it from you.
What a MotorRegistry report shows
- Official PPSR certificate Official PPSR certificate from the Australian Government's register
- Finance owing Any security interest (finance owing) registered against the vehicle, explained in plain English
- Written-off, stolen and rego checks Written-off, stolen and registration checks
- 14-day finance re-check Free 14-day finance re-check, with an email if the finance status changes
- Market valuation Independent market valuation, to compare against the asking price
What a vehicle finance check shows
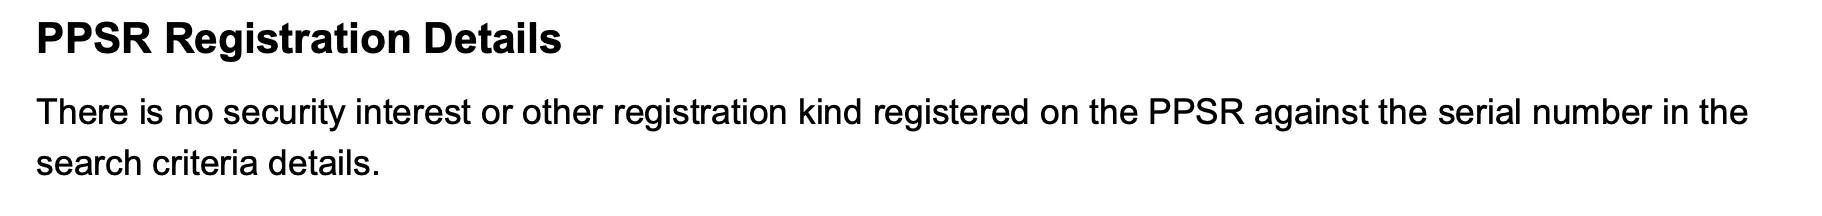
When a lender finances a car, it registers a security interest against the vehicle's VIN on the Personal Property Securities Register (PPSR), the Australian Government's national register. The security interest gives the lender the right to repossess the car if the loan isn't repaid, and it can stay attached to the car when it's sold.
A vehicle finance check searches the PPSR for any security interest registered against the car. Every MotorRegistry report includes the official PPSR certificate, with the result explained in plain English, along with the written-off, stolen and registration checks. Our PPSR check and REVS check pages cover the register in more detail. The PPSR replaced the state registers, including NSW's REVS, in 2012.
What an encumbered vehicle means
An encumbered vehicle is a car with money owing against it. The encumbrance is the lender's registered security interest: a legal claim over the car that secures the loan and stays with the car rather than the borrower. On the PPSR it appears as a security interest registered by a secured party, usually a bank or finance company. "Encumbrance" and "encumbered" are the older terms, from the days of REVS, the Register of Encumbered Vehicles, which NSW, Queensland and WA ran before the PPSR replaced the state registers in 2012.
A car can be encumbered for reasons other than a car loan. A work ute can be security for a business loan, and any car can be put up as security for a personal loan. Whatever the reason, the check shows the same thing: a security interest registered against the VIN. Searching the PPSR is the only way to find out whether a car is encumbered. Registration papers and state rego checks don't show finance.
How common is finance owing?
The rate barely changes from state to state, but it varies a lot by vehicle, with work utes carrying the highest rate. Our analysis of finance owing on used vehicles has the full breakdown.
If the check shows finance owing
Finance owing doesn't have to stop the sale, as long as the loan is paid out as part of it. Before you pay:
- Ask the seller for a payout letter from their lender showing the amount needed to clear the loan.
- Arrange for that amount to go to the lender directly, and the balance to the seller. Many lenders will manage this with the buyer and seller together.
- Get written confirmation from the lender that the loan has been paid out.
- Check the PPSR again to confirm the security interest has been removed before you take the car.
The PPSR certificate names the lender but not how much is owing, so the payout letter has to come from the seller.
The seller says the loan is paid off
A common situation: the check shows finance owing, and the seller says they paid the car off months ago. They may be telling the truth. Lenders are required to remove a registration within five business days of the loan being paid out, but it doesn't always happen, and the seller usually has no idea it's still there. Until the registration is removed, the car is still encumbered as far as the PPSR and any future buyer are concerned, so don't take the seller's word for it.
How to verify it:
- Ask the seller for the lender's payout or discharge confirmation letter. This is the letter the lender sends when the final payment clears, and the seller can request a copy if they've lost it.
- Match the lender on the letter to the secured party named on the PPSR certificate. If they're different lenders, the car has a second loan against it.
- Have the seller ask the lender to end the registration, then search the PPSR again. Only a search that comes back clear protects you.
If the lender won't act, the seller can serve it with a written amendment demand under the Personal Property Securities Act. The lender then has five business days to remove the registration before the seller can ask the PPSR Registrar to remove it instead. Make the sale conditional on a clear result, and don't hand over the money until you have one.
How long until a discharged loan leaves the PPSR
When a car loan is paid out, the lender has to end its registration within five business days. Most do it within a day or two of the final payment clearing, so a car paid off a month ago should already show as clear. If it doesn't, the lender has missed its deadline or the final payment hasn't cleared yet, and the seller should chase them before you search again.
Don't confuse this with the registration's end date on the certificate. A lender can register a security interest over a car for up to seven years at a time and renew it, so a registration can show an end date years away on a loan that was paid off last week. The end date tells you how long the registration was set to run, not how much of the loan is left.
Can a car be repossessed from a new owner?
Yes. A security interest attaches to the car, not to the person who took out the loan. If you buy a car with finance owing and the seller stops paying, the lender can repossess the car from you, even though you paid for it in full and never had anything to do with the loan. You don't take on the seller's debt, but to keep the car you'd generally have to pay the lender out and then pursue the seller for the money.
The PPSR protects buyers who check. If you buy from a private seller and a search by the car's VIN immediately before the sale shows no security interest, you generally take the car free of any finance that wasn't registered. That's why a search from a few weeks ago isn't enough: the protection depends on the result being current at the time you pay.
Comprehensive and Comprehensive Plus reports include a free 14-day finance re-check that covers the gap between reading the report and handing over the money. If the vehicle's finance status changes in that time, we email you.
Check as close to payment as you can
A PPSR search reflects the register at the moment it's run. If you buy from a private seller and a search shows no security interest against the vehicle's serial number, you generally take the car free of any undisclosed finance. That protection depends on the search being current, and a car can be refinanced between the day you check it and the day you pay.
Comprehensive and Comprehensive Plus reports include a free 14-day finance re-check. We check the PPSR again after you buy the report and email you if the vehicle's finance status changes, so you're not relying on a result from a week ago. Our FAQ explains how the 14-day finance re-check works.
Buying from a dealer
Licensed dealers must give you clear title to the vehicle, so finance owing is mainly a risk in private sales. A check is still worth running on a dealer car. It confirms the written-off and stolen status too, and the dealer's own paperwork won't include the car's wider history.
Vehicle Finance Check FAQ
How do I check if a car has finance owing?
Search the car's VIN on the Personal Property Securities Register (PPSR). Lenders register their security interest in a financed vehicle on the PPSR, so a search shows whether money is owed against it. Every MotorRegistry report includes the official PPSR certificate from a rego or VIN search.
What happens if I buy a car with finance owing?
The lender's security interest can stay attached to the car after it's sold, so the lender may be able to repossess it from you if the seller doesn't pay the loan out. You would then have to pursue the seller for your money.
Does a PPSR certificate protect me?
If you buy from a private seller and a PPSR search shows no security interest registered against the vehicle's serial number, you generally take the car free of any undisclosed finance. The protection depends on the search being current, so search as close to the time of purchase as you can. Comprehensive and Comprehensive Plus reports include a free 14-day finance re-check that emails you if the finance status changes.
Can the report tell me who the loan is with or how much is owing?
It names the lender, but not the amount. The PPSR certificate shows the secured party that registered the interest, usually a bank or finance company, but the amount owing isn't available to buyers from the PPSR or anywhere else. If a report shows finance owing, ask the seller to arrange a payout letter from that lender and settle the loan as part of the sale, then check again before you pay.
How common is finance owing on used cars?
About 1 in 10 used vehicles checked with MotorRegistry has finance owing. The rate is higher for some vehicle types, particularly work utes. Our blog post on finance owing has the breakdown by vehicle and state.
What does it mean if a car is encumbered?
An encumbered car has a security interest registered against it on the PPSR, usually because a lender financed it and the loan hasn't been paid out. The lender can repossess the car if the loan isn't repaid, and that right stays with the car when it's sold. 'Encumbered' and 'encumbrance' come from the old state REVS registers (Register of Encumbered Vehicles) that the PPSR replaced in 2012.
The seller says the car is paid off but the check shows finance owing. Who's right?
Possibly both. Lenders have to remove a registration within five business days of a loan being paid out, but some miss it. Ask the seller for the lender's payout or discharge letter, check it names the same lender as the PPSR certificate, and have the seller get the registration removed. Then search again, and don't pay until the result is clear.
How long after paying off a car loan does it come off the PPSR?
The lender must end its registration within five business days of the loan being paid out, and most do it within a day or two of the final payment clearing. If a car paid off weeks ago still shows finance owing, the seller needs to chase the lender. The registration's end date on the certificate isn't a guide: lenders register for up to seven years at a time regardless of the loan term.
Start with a PPSR check or a full car history check.
Check the car before you pay
Enter the rego or VIN to see what's on record for the vehicle.
Check a vehicle now
